Dr Jabulani Dhlamini
Zimbabwe’s informal economy should no longer be viewed principally through the lens of exclusion from social security.
It should also be viewed as an opportunity to expand the National Social Security Authority (NSSA)’s contributor base and build a much larger pool of long-term social security capital.
The question is how to achieve this without simply transferring an enormous future pension liability to the Government.
In setting a strategy for NSSA, the starting point should be a fundamental question: How large should the authority’s asset base ultimately be?
As argued in my earlier article published on September 27, 2026, this target should anchor efforts to expand the contribution base and determine the contribution levels required from current and potential members.
This changes how the informal sector can be viewed. Rather than seeing informal workers primarily as people outside the social security system who may eventually require support, they should also be regarded as potential contributors to a larger national social security capital base.
The strategic challenge, therefore, is not simply to bring more people into NSSA. It is to design a contribution system that is sufficiently accessible, flexible and attractive to enable millions of economically active Zimbabweans to participate.
For many informal sector workers, a traditional monthly contribution model may not reflect how income is earned.
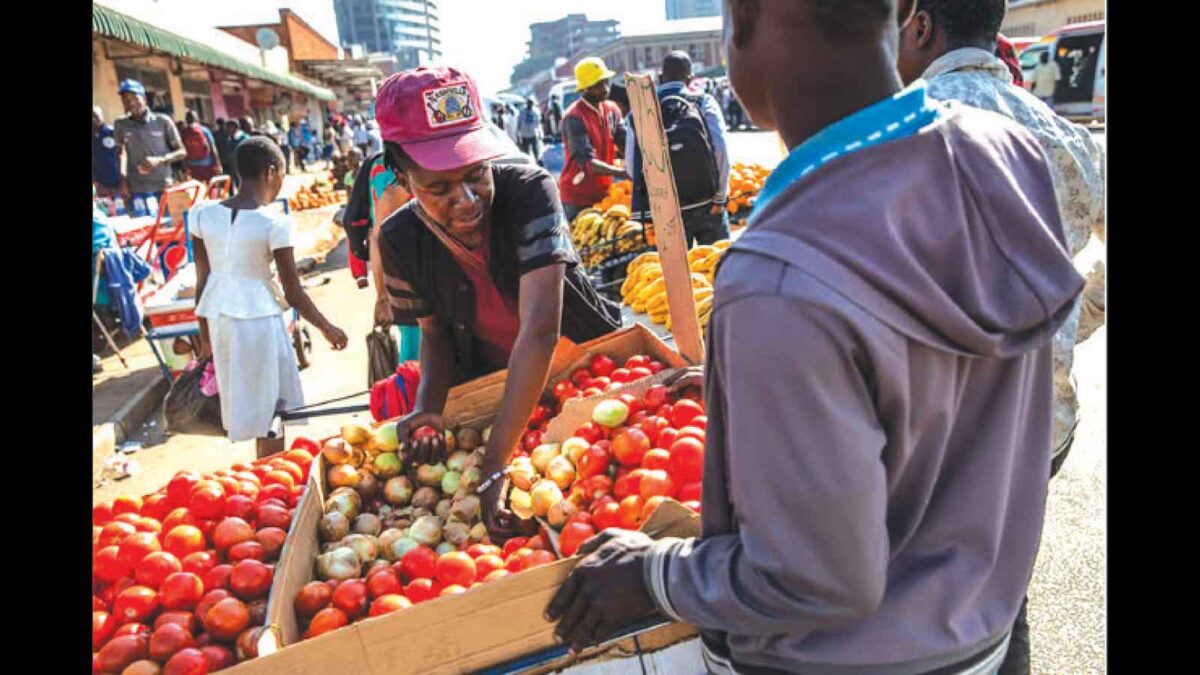
A market trader, informal manufacturer, transport operator, farmer or small service provider may receive income daily, weekly or irregularly.
NSSA could, therefore, consider a flexible contribution model allowing members to contribute daily, weekly, monthly or periodically, depending on their income patterns.
Digital payment platforms and mobile money channels could make contributions easier to collect and administer.
The objective should be to make participation simple, transparent and worthwhile. Contributors should be able to see their contributions, any Government-supported contributions and the benefits they are building towards.
This transparency is essential for building trust in NSSA and giving members confidence about what the authority can deliver for them in the future.
The Government could play a catalytic role in encouraging participation.
For example, targeted matching contributions could be considered for defined categories of informal workers.
A worker contributing US$10 might receive an additional US$5 from the Government, subject to the scheme’s design, fiscal capacity and appropriate policy and legislative arrangements.
Other mechanisms could include allocating a defined portion of selected revenues or levies to support participation by lower-income contributors. Such arrangements would require careful fiscal and policy analysis.
The underlying principle is important: Government support could help citizens build social security capital rather than simply finance future liabilities.
If millions of Zimbabweans become contributors to a properly structured social security system, even relatively small individual contributions could collectively create a substantial pool of long-term capital.
However, expanding the contributor base should not be an end in itself. It must be linked to a clearly defined strategy for growing NSSA’s assets and meeting its future obligations.
This requires understanding the relationship between the desired asset base, the number of contributors, contribution levels, investment returns and future social security commitments.
An actuarial assessment should provide the foundation for determining the required fund size, identifying any funding gap and establishing appropriate contribution and investment growth requirements. The NSSA Act provides for actuarial assessment of the fund.
The strategic questions are, therefore, interconnected: What level of social protection should NSSA provide? What asset base is required to support it? How many contributors are needed? What should they contribute? What investment returns are necessary and what role should the Government play?
Answering these questions would provide a systematic basis for developing an integrated NSSA strategy in which informal sector inclusion becomes an important mechanism for growing the authority’s contributor base and assets.
A larger contributor base will create long-term value only if the resulting funds are prudently managed and generate sustainable, risk-adjusted returns.
Informal-sector expansion should, therefore, form part of an integrated strategy linking coverage, contributions, asset growth, investment performance and social protection. Achieving this will require appropriate contribution mechanisms, digital collection systems, incentives for participation, actuarial modelling, disciplined investment management and strong governance.
Most importantly, the strategy should begin with the end in mind.
NSSA must first establish the capital base required to support its long-term social-protection ambitions.
From that target, the required contributor base, contribution levels, Government support and investment returns can be determined.
A substantially larger pool of professionally managed social security capital could also contribute to Zimbabwe’s long-term development financing needs through appropriate investments while preserving NSSA’s primary responsibility to contributors and beneficiaries.
The informal sector is, therefore, not merely a coverage gap.
It could become one of the foundations of a much larger NSSA capital base.
The strategic challenge is to develop an institutional framework capable of converting millions of relatively small contributions into a sufficiently large pool of professionally managed capital while providing meaningful and sustainable social protection to the people who create it. That shift — from coverage gap to capital base — could be an important part of the next phase of NSSA’s development.
Dr Jabulani Dhlamini is a strategic management professional and real estate consultant with more than two decades of experience spanning strategy formulation, strategic planning facilitation, corporate entrepreneurship, organisational restructuring, governance, SME (small and medium enterprise) development, strategic risk management and real estate development and advisory. Contact details: +263 781 322 478, [email protected], Website: http://www.jabulanidhlamini.com/