Online Reporter
Business Writer
Zimbabwe will introduce Domestic Minimum Top-Up Tax, to be applied in retrospect on 1 January 2026, with regulations to operationalise the tax expected before the end of next month, a senior tax authority official said.
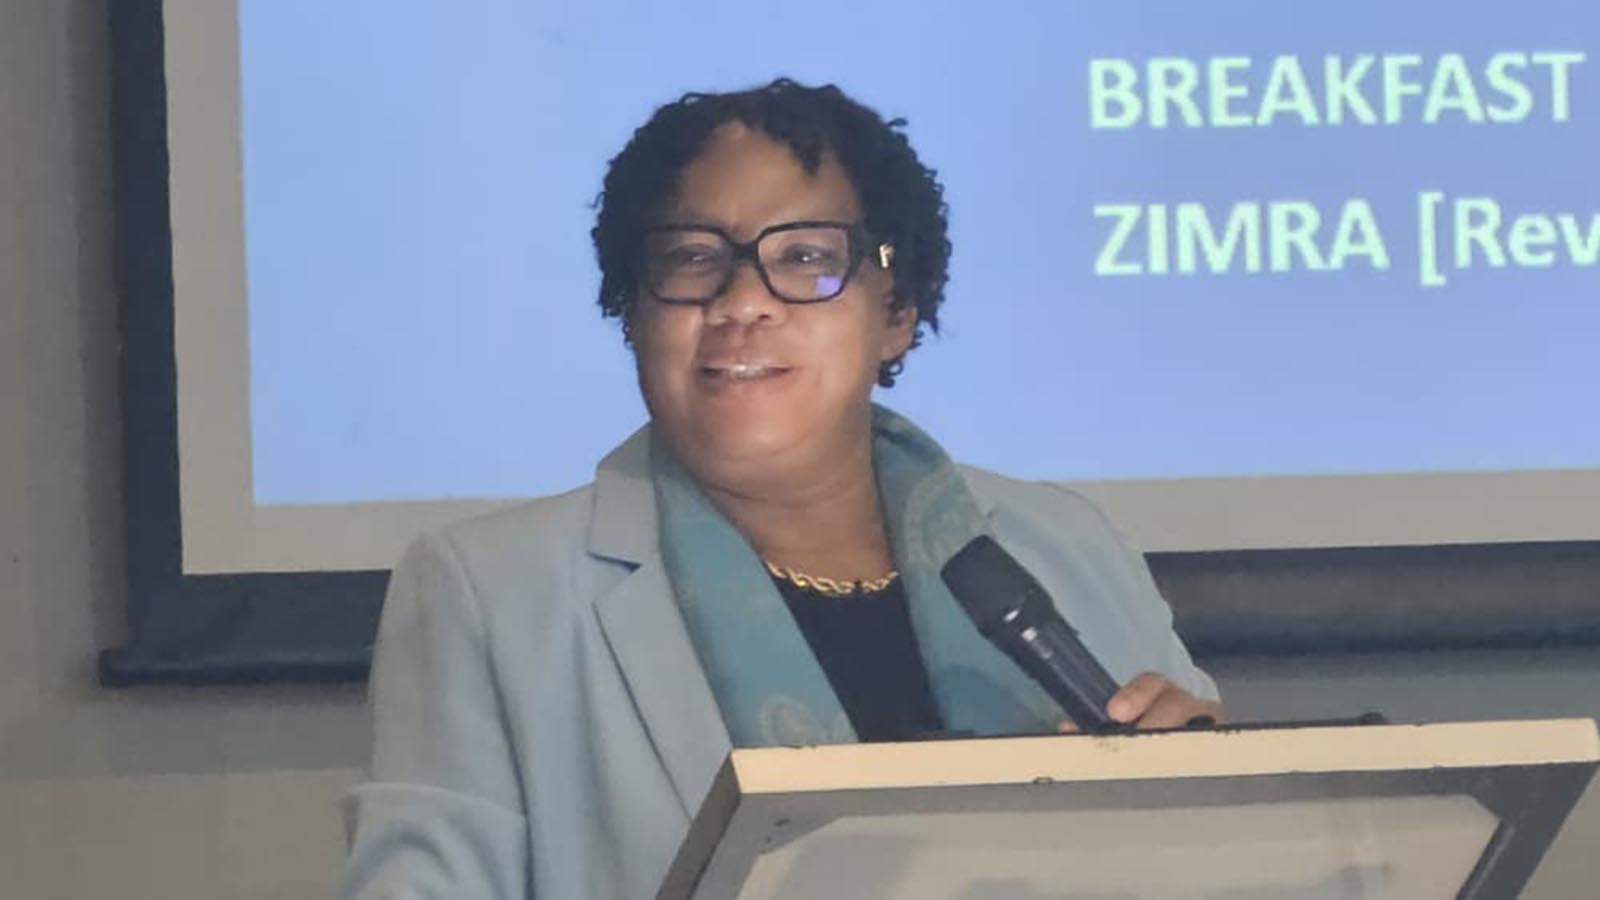
Addressing stakeholders at a breakfast engagement in Harare yesterday, Zimbabwe Revenue Authority (ZIMRA) Commissioner Revenue Assurance, Mrs Constance Shumbayawonda, said the principal law was now in place.
A Domestic Minimum Top-Up Tax (DMTT) or Qualified Domestic Minimum Top-Up Tax (QDMTT) is a local tax mechanism that ensures large multinational enterprises pay a minimum effective corporate tax rate of 15 percent on income generated within a country.
Reporting and processing under the Domestic Minimum Top Up Tax (DMTT), Mrs Shumbayawonda said, had been made seamless, with only the regulations outstanding.
“What is left now is only the regulations. We are in an advanced stage. Our chief director (from the Ministry of Finance, Economic Development and Investment Promotion) is here.
“As soon as he is done with the regulations. . . we are hoping to push them through before the end of the coming month,” she said.
She said the introduction of the DMTT represented both a strategic measure to safeguard Zimbabwe’s taxing rights and an economic imperative to protect the domestic tax base in an increasingly interconnected global economy.
Mrs Shumbayawonda explained that before the legislation, if a multinational company operating in Zimbabwe paid an effective tax rate of less than 15 percent — for example, because of tax incentives or concessions offered by Zimbabwe — another country, such as the jurisdiction where its parent company is based, would potentially collect the additional tax needed to bring the effective rate to 15 percent.
“By enacting the DMTT, we ensure that the primary rights to tax the profits generated right here in Zimbabwe remain with Zimbabwe,” she said. “This legislation prevents the flight of tax revenues, preserves fiscal sovereignty and ensures a level playing field.”
She said governments across the world have been responding to the challenges posed by base erosion and profit shifting by multinational enterprises that exploit cross-border mismatches to shift profits out of source jurisdictions into low-tax jurisdictions. In response, she said, the Organisation for Economic Co-operation and Development (OECD/G20 (Group of Twenty) Inclusive Framework developed the Two-Pillar Solution, with Pillar Two establishing a global minimum corporate tax rate of 15 percent.
Mrs Shumbayawonda said Zimbabwe’s engagement and re-engagement with international tax frameworks was genuine and reinforced efforts to build a transparent, internationally connected and effective tax administration.
She said joining the multilateral convention brought Zimbabwe into a powerful network of more than 160 jurisdictions, equipping it with tools for robust cross-border cooperation, including automatic exchange of information to clamp down on illicit financial flows and secure a fair share of revenue.
“Our intention goes beyond aligning with evolving international tax standards. We seek to have a meaningful voice at the table, articulate Zimbabwe’s domestic and developmental priorities, and contribute to ongoing international tax discussions,” she said.
On implementation, she said Zimbabwe had taken proactive and concrete steps to ensure a smooth transition through capacity building.
“We have aggressively trained a dedicated team of specialists within our organisation who thoroughly understand the Pillar Two mechanisms,” she said, adding that the technical team was being deployed countrywide to assist affected entities.
She said ZIMRA was also finalising comprehensive technical guidance and general regulations to simplify compliance and stressed that the authority did not view itself merely as a collector of revenue.
“We do not view ourselves merely as collectors, but as partners in compliance. That is revenue assurance,” she said.
“Our goal is to ensure that by the time the first filing deadline arrives next year, every affected corporate entity and consultant in this room feels fully equipped, informed and supported by ZIMRA.”
Mrs Shumbayawonda said the breakfast engagement provided an important platform for dialogue, knowledge sharing and mutual understanding and urged stakeholders to approach the discussion in a spirit of partnership.
“Today is not the end. It is only the beginning of more engagements that will help. You can still engage with my office and they are free to assist you,” she said.
The Domestic Minimum Top Up Tax was enacted through the Finance Act and takes effect retrospectively on 1 January 2026.