Online Reporter
Nelson Gahadza
AS the African Continental Free Trade Area (AfCFTA) progressively alters barriers separating national markets, the question for Zimbabwean companies is no longer how to survive domestically, but whether they possess the scale, capital and operational capacity to compete beyond the country’s borders.
Success in a liberalised continental market depends not only on ambition, but also on the financial depth to fund expansion, absorb risk and sustain operations across multiple jurisdictions.
That makes mergers and acquisitions (M&A) more than transactions; they should be viewed as an industrial strategy through which Zimbabwe can build larger, better-capitalised and regionally competitive businesses.
The AfCFTA brings together 55 countries and about 1,3 billion people, with a combined economic output of roughly US$3,4 trillion.
For Zimbabwean companies, access to this market will not automatically translate into competitiveness.
The continental market will expose local businesses to companies operating at considerably greater scale, with deeper pockets, wider distribution networks and stronger access to technology and finance.
The strategic response should be to build scale before competitive pressure becomes overwhelming.
There are already signs of movement in this direction.
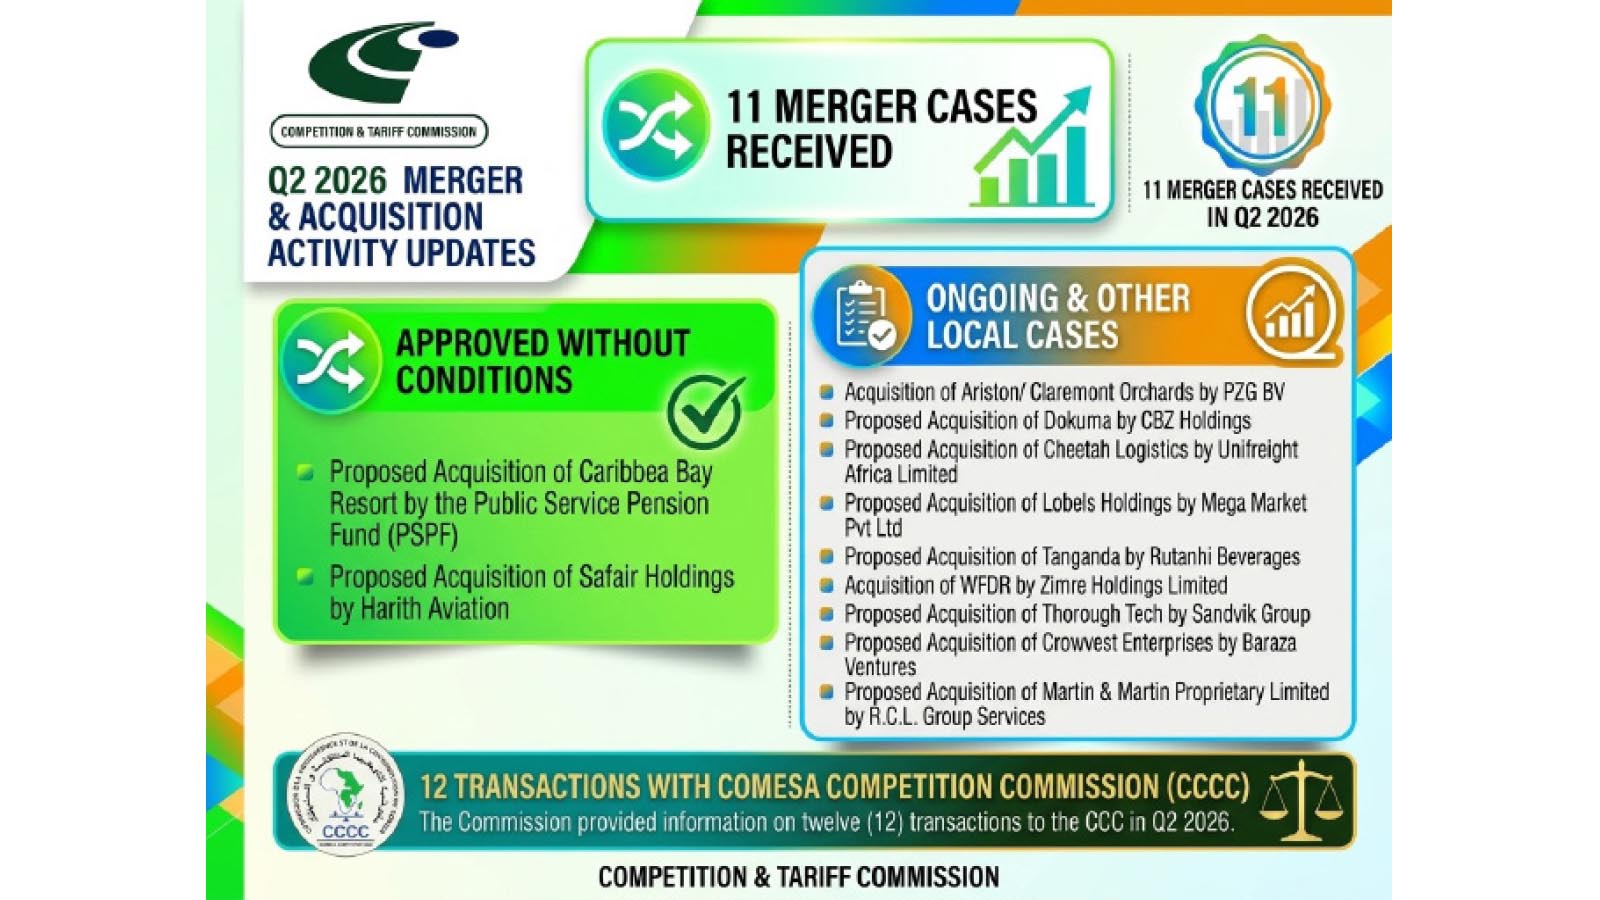
The Competition and Tariff Commission (CTC) received 11 merger and acquisition cases in the second quarter of 2026, with two approved without conditions and nine still under consideration.
This is in addition to seven merger transactions handled in the first quarter.
In 2025, the commission handled 30 merger cases, approving 26.
In September 2026, the CTC launched an investigation into Varun Beverages’ proposed acquisition of a 48,79 percent stake in Dairibord Holdings, while approving Mega Market’s acquisition of Lobels Holdings with conditions designed to protect competition.
The collapse of the proposed US$2,5 billion CBZ-ZB merger offers a cautionary tale about the regulatory balance between scale and competition.
The deal collapsed after CBZ rejected the CTC’s stringent conditions, which included mandatory divestments from Mashonaland Holdings, ZB Re and Cell Insurance, and a requirement to maintain separate banking brands.
The CTC identified serious competition concerns: potential collusion in reinsurance and property, market foreclosure and the risk of the Government directing business to a single dominant player.
CBZ board chairperson Mr Luckson Zembe expressed frustration, arguing that Zimbabwe needs institutions capable of mobilising “not less than US$20 billion annually” to transform the economy.
The collapse underscores a fundamental tension: Zimbabwe needs large, well-capitalised institutions to compete under AfCFTA, but the CTC must prevent excessive concentration that harms consumers and smaller competitors.
One of the CTC’s mandates is studying trends towards increased economic concentration, with a view to preventing monopoly situations contrary to the public interest.
This narrow domestic-market framing may no longer be sufficient, according to Kudzanai Sharara, head of Business and Events Hub at Zimpapers.
“As AfCFTA reshapes the competitive landscape, the CTC should broaden its assessment to consider whether a proposed acquisition is designed to strengthen a company’s balance sheet for continental exposure, rather than merely entrenching domestic market power,” he said.
“A merger that might raise concentration concerns locally could, in fact, be the very mechanism that gives a Zimbabwean firm the capital base, scale and operational capacity needed to compete against larger regional players.
“The commission’s mandate should, therefore, evolve to weigh competitive effects within Zimbabwe against the strategic imperative of building nationally rooted corporates capable of underwriting expansion across Africa.”
Without consolidation, Zimbabwean firms will struggle against subsidised, large-scale producers from across Africa.
M&A offers economies of scale, reduced input costs through bulk purchasing and the financial strength to invest in modern production facilities.
Varun’s planned US$650 million investment in Zimbabwe’s FMCG (fast-moving consumer good) manufacturing, agriculture and renewable energy demonstrates the kind of capital injection that local firms cannot generate organically.
The proposed acquisition of a 48,79 percent stake in Dairibord Holdings by Varun Beverages (Zimbabwe) illustrates why M&A is likely to occupy an increasingly prominent position in Zimbabwe’s corporate landscape.
The CTC is investigating whether the transaction could substantially lessen competition or create a monopoly situation, with stakeholders invited to submit representations ahead of the October 1, 2026 deadline.
The deal would bring together two businesses with significant positions in Zimbabwe’s food and beverage value chain.
Varun, the local franchise bottler for PepsiCo, has invested more than US$100 million in Zimbabwe since establishing its Harare greenfield operation in 2018.
Dairibord is the country’s largest processor and distributor of dairy products, food and beverages. Its own corporate history demonstrates how acquisitions can be used to create scale: The company acquired 100 percent of the Lyons Zimbabwe business in 2001 and subsequently developed a holding-company structure incorporating several businesses.
Trigrams Investments analyst Mr Wafa Kuchera said Zimbabwe’s relatively small domestic market made scale particularly important as the continental market opened up.
“Zimbabwe is a small market with a population of just 16 million and a GDP (gross domestic product) estimate of around US$40 billion,” he said. “The AfCFTA, on the other hand, encompasses a massive single market of over 1,4 billion people with a combined GDP of approximately US$3,4 trillion.
“In this scenario, Zimbabwean corporates need to pool resources such as skills, equipment and capital to be able not only to compete, but to also become vital cogs in the value chains that are being created. As the continent opens up, the size of corporate operations and the depth of skills will matter more and more.”
Mr Kuchera said sectors linked to agriculture and agro-processing, mining, logistics, financial and insurance services were likely to see increased M&A activity, with Zimbabwe’s geographical position also presenting opportunities in aviation, road and rail logistics.
Investment analyst Mr Enock Rukarwa said the reduction in trade barriers under AfCFTA would favour companies with the financial muscle to operate at scale.
“So, obviously, the companies that are going to benefit are those that can operate at a large scale, companies with massive balance sheets and a massive capital base,” he said, adding that M&A would bring the balance sheet support, capital base and economies of scale needed to compete regionally.
The financial services sector provides another illustration of how consolidation can expand corporate scale.
CBZ Holdings’ acquisition of a controlling stake in First Mutual Holdings in 2023 demonstrated how a financial services group could broaden its business beyond traditional banking, with CBZ chief executive officer Mr Lawrence Nyazema saying the group wanted to diversify, deepen its Zimbabwean operations and ultimately expand internationally.
There is also evidence that Zimbabwe’s corporate sector can execute transformational transactions.
FBC Holdings completed its acquisition of 100 percent of Standard Chartered Bank Zimbabwe in 2024, demonstrating how a domestic financial institution could acquire the assets and customer base of an international banking group, while expanding its own corporate footprint.
The dairy sector has also experienced consolidation, after the CTC approved the acquisition of Dendairy by Vamara Group and 3DZ Capital, subject to conditions requiring fair and non-discriminatory treatment of suppliers and customers.
The logistics industry has similarly seen Unifreight acquire Nimbcon Trading, while in tourism, Rainbow Tourism Group acquired Briolette Services.
“These transactions point to an emerging corporate landscape in which consolidation is becoming an increasingly important mechanism for reshaping businesses,” said economist Mr Walter Mapfumo.
He said the AfCFTA will reward scale, as well as efficiency.
“The agreement is not simply about removing tariffs. Companies seeking to take advantage of the continental market will have to comply with rules of origin, standards, certification requirements and other regulatory conditions,” he said.
Zimbabwe has been developing capacity around AfCFTA rules of origin, including through training involving the Zimbabwe Revenue Authority (ZIMRA).
The World Bank has also stressed that reducing trade costs, improving customs procedures and addressing non-tariff barriers will be critical to unlocking AfCFTA’s potential.