Sunday Mail Correspondent
PROPERTY developers and construction industry players are exploring a new financing model that could pool land assets to mobilise investment capital and potentially establish a dedicated housing and construction development bank, as the country seeks innovative solutions to accelerate housing delivery.
The proposal emerged from the third annual Zimbabwe Real Estate and Construction Summit, held in Harare from October 28 to 31, which brought together institutional financiers, property developers, construction executives and other stakeholders to examine financing constraints, infrastructure investment, property development and opportunities for greater participation by local contractors.
Central to the discussions was the shortage of affordable long-term finance for both developers and prospective homeowners, a challenge that continues to affect the speed and scale of housing delivery. In the absence of widely accessible mortgage financing, many developers have relied on instalment-based stand sales to finance infrastructure and development activities.
While this model has enabled some projects to progress, stakeholders warned that it can prolong construction timelines, constrain working capital and limit the number of housing units delivered. Industry players are, therefore, calling for a fundamental shift from financing housing primarily through buyers’ instalments towards structured development finance, mortgage lending and institutional investment.
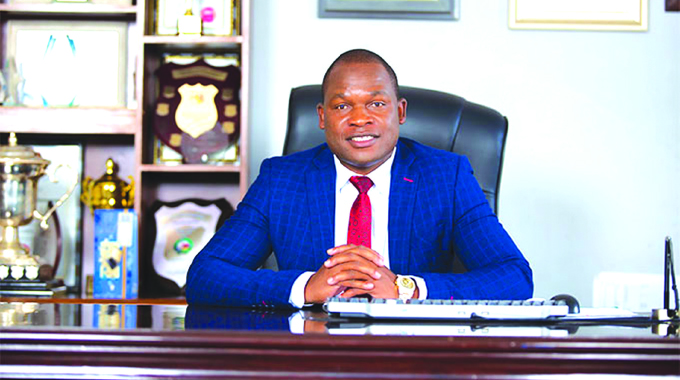
Speaking at the summit, Zimbabwe Building Contractors Association president Dr Tinashe Manzungu pointed to international precedents, including the Federal Mortgage Bank of Nigeria, an institution established to support Nigeria’s housing finance system.
Through the National Housing Fund and associated financing arrangements, the bank facilitates access to housing finance for qualifying contributors while supporting developers involved in residential construction.
“The institution’s estate development financing arrangements are particularly relevant to Zimbabwe, where developers frequently struggle to obtain affordable funding for roads, water systems, sewerage infrastructure and housing construction,” Dr Manzungu said.
He also cited the Nigeria Mortgage Refinance Company, which was established to improve mortgage market liquidity by providing refinancing to participating mortgage lenders. Together, he said, such institutions illustrate how dedicated housing finance mechanisms can address both sides of the property market: the developer who requires capital to build and the homeowner who needs long-term financing to purchase.
A potentially transformative proposal discussed at the summit is the creation of a consortium of established Zimbabwean land developers who would collectively mobilise their landholdings to support a new development financing institution.
Bringing together developers holding residential, commercial, industrial and mixed-use development land would create a consolidated asset portfolio. Subject to independent valuation, ownership verification and appropriate legal structuring, these land assets could be contributed to an investment holding company or project-specific vehicles.
The consortium could then use its asset base to attract equity investors, negotiate development financing and explore the establishment of a specialised housing and construction development bank. There were also references to the Kenya Mortgage Refinance Company, established in 2018, which operates as a specialised, non-deposit-taking financial institution that provides long-term funding to banks and savings and credit cooperatives for mortgage lending. Dr Manzungu also emphasised the importance of domestic enterprise development.
“Beyond mortgage financing, our infrastructure investment must support domestic enterprise development,” he said.
“A dedicated construction financing institution could potentially introduce specialised facilities for equipment acquisition, working capital, contract mobilisation and infrastructure development, enabling indigenous companies to compete more effectively.”
The proposed financing model also creates significant opportunities for collaboration with African and international development finance institutions, including the African Development Bank, Shelter Afrique Development Bank and African Export-Import Bank (Afreximbank). As Zimbabwe pursues its Vision 2030 objectives, the establishment of a housing and construction development bank, potentially supported by a consortium of land developers, is being touted as an ambitious initiative requiring careful planning, sound regulation and broad stakeholder participation.
MCM Estates chief executive officer Mr Anthony McMullen said the strategic alignment among developers to pool land assets could fundamentally re-engineer Zimbabwe’s property market, transforming illiquid land reserves into robust institutional equity that unlocks structured development finance and drives large-scale housing delivery.
“This strategic convergence on land-backed financing frameworks signals a pivotal paradigm shift. By aggregating collective land assets into institutional-grade equity vehicles, we can systematically de-risk capital deployment, catalyse large-scale infrastructural development and circumvent traditional liquidity bottlenecks to accelerate sustainable housing delivery.”