Martin Kadzere
Zimbabwe’s ferrochrome producers are lobbying the Government for a concessionary electricity tariff of US$0,07 per kilowatt-hour (kWh) in 2027, warning that uncompetitive power costs and outstanding electricity tariff liabilities have left nearly two-thirds of the country’s smelting furnaces idle.
According to the Chamber of Mines of Zimbabwe’s Mining Prospects 2027: The State of the Mining Industry Survey Report, released this week, producers are seeking the reduced tariff for the period from January 1 to December 31, 2027, together with full waivers on accumulated tariff variances.
Under an interim arrangement for 2026, smelters have been paying US$0,08 per kWh against an invoiced tariff of US$0,10.
However, even at the reduced rate, local smelters say they remain uncompetitive against major global producers, citing preferential ferrochrome electricity tariffs of about US$0,038 per kWh in South Africa and industrial rates averaging around US$0,06 per kWh in China’s major ferroalloy production hubs.
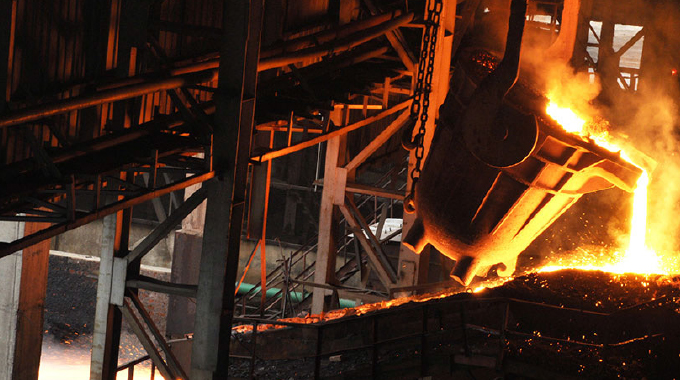
The Chamber of Mines report says high electricity costs have significantly constrained local beneficiation, with only 15 of Zimbabwe’s 41 installed ferrochrome furnaces operational.

This has kept industry capacity utilisation subdued, with the subsector expected to operate at just 36 percent in 2026.
The report warns that high electricity tariffs and generation shortfalls threaten to undermine mining expansion and mineral beneficiation targets.
Beyond seeking a reduction to US$0,07 per kWh in 2027, producers are also appealing for the cancellation of two separate accumulated tariff balances reflected as liabilities on their books.
Between October 2022 and December 2023, smelters paid a concessionary rate of US$0,08 per kWh against an approved mining tariff of US$0,1221.
ZESA has maintained its claim to recover the US$0,0421 per kWh difference, a liability producers want waived to prevent further financial pressure and potential furnace closures.
Under the current interim framework, the unpaid US$0,02 per kWh difference between the invoiced tariff of US$0,10 and the US$0,08 paid by smelters is recoverable in cash or electricity units once individual producers commission their own power plants.
However, producers are seeking an unconditional write-off of this outstanding balance, irrespective of when their captive power plants are commissioned, citing substantial capital commitments towards self-generation projects.
The survey indicates that granting the proposed US$0,07 tariff and clearing accumulated tariff variances could trigger a significant recovery in the subsector.
Average ferrochrome capacity utilisation is projected to increase from 36 percent in 2026 to 90 percent in 2027 as currently idle furnaces resume operations.
“Producers are appealing for a full waiver on the accumulated deferred tariff amount in full, without requiring subsequent recovery through cash payments or equivalent electricity units, irrespective of the respective CPP (captive power plants) commissioning dates in view of the significant financial commitments on captive power projects,” said the report.
To support the anticipated increase in smelting activity, domestic chrome ore production is forecast to rise to 2,7 million tonnes in 2027, from approximately two million tonnes expected in 2026.
However, producers warn that without urgent tariff relief, high operating costs will continue to constrain furnace restarts and erode Zimbabwe’s competitiveness in regional and international chrome beneficiation markets.
Zimbabwe’s ferrochrome industry is a strategic pillar of the country’s mineral beneficiation agenda, generating foreign currency, creating employment and supplying a critical raw material to the global stainless steel value chain.
The country’s chromite resources are concentrated along the 550-kilometre Great Dyke, which hosts the world’s second-largest chromite reserves, accounting for approximately 12 percent of global reserves.
Zimbabwe’s deposits, estimated at 560 million tonnes in proven reserves and more than one billion tonnes in broader resources, are also distinguished by their high chromium-to-iron ratio, giving the country a competitive advantage in ferrochrome production.
To maximise domestic value addition and protect local smelters from feedstock shortages, the Government maintains restrictions on raw chrome ore exports.
Although authorities have occasionally granted special exemptions, including temporary waivers for miners without local smelting capacity and the disposal of unmarketable ore stockpiles, ferrochrome producers have consistently advocated for strict enforcement of the export restrictions.
They argue that retaining chrome ore within the country would ensure adequate feedstock for domestic smelters and maximise value addition through its processing into higher-value ferrochrome.