Online Reporter
Dr Jabulani Dhlamini
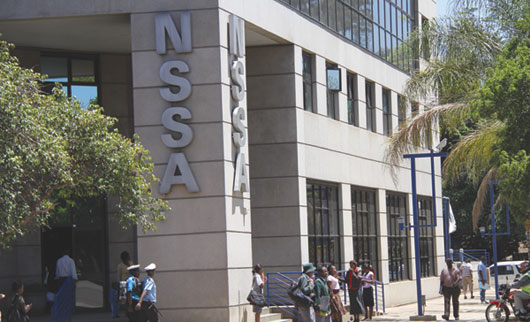
BUT there is a more fundamental question that Zimbabwe needs to confront: How large must the National Social Security Authority (NSSA) become if it is to provide meaningful social protection not only to today’s pensioners, but also to tomorrow’s?
This question is becoming increasingly important as the structure of Zimbabwe’s labour market changes.
NSSA was established in 1989 primarily to provide social security to workers who were formally employed and contributing through registered employers.
That model made sense in an economy where formal employment was the dominant means through which people participated in the labour market. Today, however, the structure of employment presents a very different challenge.
Data analysed in our study, based on Zimbabwe National Statistics Agency (ZimStat) and NSSA information, illustrates the scale of the challenge.
In 2022, Zimbabwe had an estimated 896 767 formal employees, compared with approximately 2,23 million informal employees.
In other words, 71 percent of the active workforce was classified as informal. This creates a fundamental structural problem.
The people who are easiest for NSSA to identify and collect contributions from are those attached to registered employers.
Yet the majority of economically active people are outside this traditional employment relationship. The issue is, therefore, not simply that NSSA needs to collect more money from existing contributors.
NSSA needs to expand the contribution base itself.
There is an important distinction here. Informal workers are not necessarily economically inactive or unproductive.
They include traders, entrepreneurs, farmers, artisans, small business operators and many others who generate income outside conventional employer-employee relationships. The challenge is that the social-security system has historically been designed around the formal employment relationship.
Zimbabwe, therefore, needs to start thinking about social security differently.
The objective should be to progressively build a national social protection asset base capable of supporting citizens through old age, disability, occupational injury and other periods when they can no longer earn an income.
This requires two things: more contributions going into the system and stronger growth of the assets generated from those contributions.
The first priority should be to ensure that every eligible formal employer is contributing.
NSSA can work more closely with institutions such as the Zimbabwe Revenue Authority (Zimra), the Companies Registry and the Labour Department to identify registered businesses that are not fulfilling their obligations. Better compliance would immediately broaden the existing contribution base.
The bigger opportunity, however, lies in the informal economy.
A future social-security architecture should provide practical mechanisms through which informal workers can contribute.
This could include appropriately designed voluntary contributions, simplified digital payment mechanisms and, subject to policy and legislative decisions, mechanisms through which a portion of selected centrally collected levies could support social-security contributions for economically active citizens outside the formal system.
The principle should be simple: If people are economically active today, the system should provide a pathway for them to build social protection for tomorrow. But increasing contributions alone will not solve the problem.
The second half of the equation is what NSSA does with the assets entrusted to it.
NSSA is effectively managing a pool of capital whose ultimate purpose is social protection.
Its investment strategy, therefore, matters enormously. The objective should be to grow the fund prudently through diversified investments that generate sustainable, risk-adjusted returns while protecting contributors’ interests.
Investment decisions must be subject to strong governance, transparent oversight, independent assessment and effective strategic risk management.
The study specifically recommends that NSSA assess whether its investments are generating positive returns and whether capital should remain in existing investments or be redirected elsewhere. This is where the concept of assets under management becomes important.
The conversation should move beyond asking how much NSSA pays out this year.
We should also be asking: How large should NSSA’s asset base become over the next 10, 20 or 30 years to provide sustainable social protection to Zimbabweans?
That question requires an actuarial assessment of the size of the fund required to meet future obligations, including different scenarios incorporating both formal and informal contributors.
The NSSA Act already provides for such an assessment.
There is a sobering indicator of why this matters: Today’s informal worker is tomorrow’s elderly citizen. If that worker spends decades economically active without building social-security entitlement, the responsibility eventually shifts elsewhere — potentially to families, communities and the Government.
And this should concern all of us.
The answer cannot simply be to wait until people reach retirement age and then ask how they will be supported. We need to build the capacity before the need arises.
A stronger NSSA could, therefore, become more than a pension administrator.
With appropriate governance and investment discipline, its growing asset base could support productive investments in areas such as infrastructure, housing, education and health, while generating returns that strengthen the fund. But this requires trust.
NSSA manages resources that belong, in effect, to current and future beneficiaries. Strong corporate governance, ethical leadership, independent oversight and transparent investment decisions are, therefore, not administrative niceties.
They are essential to the preservation and growth of the social-security fund.
Zimbabwe should, therefore, adopt a long-term ambition: build a NSSA capable of providing social protection for everyone who needs it — today and in the future.
That means expanding the contribution base beyond traditional formal employment, bringing the informal economy into the social-security architecture, investing the resulting pool of capital prudently, and measuring success not only by benefits paid today but by the strength of the asset base available to pay benefits tomorrow. The ultimate measure of NSSA’s success should not simply be how many people it currently serves.
It should be whether Zimbabwe is building a social-security institution financially strong enough to protect generations yet unborn.
Dr Jabulani Dhlamini is a strategic management professional and real estate consultant with more than two decades of experience spanning strategy formulation, strategic planning facilitation, corporate entrepreneurship, organisational restructuring, governance, SME (small and medium enterprise) development, strategic risk management and real estate development and advisory. Contact details: +263 781 322 478, [email protected], Website: http://www.jabulanidhlamini.com/