Online Reporter
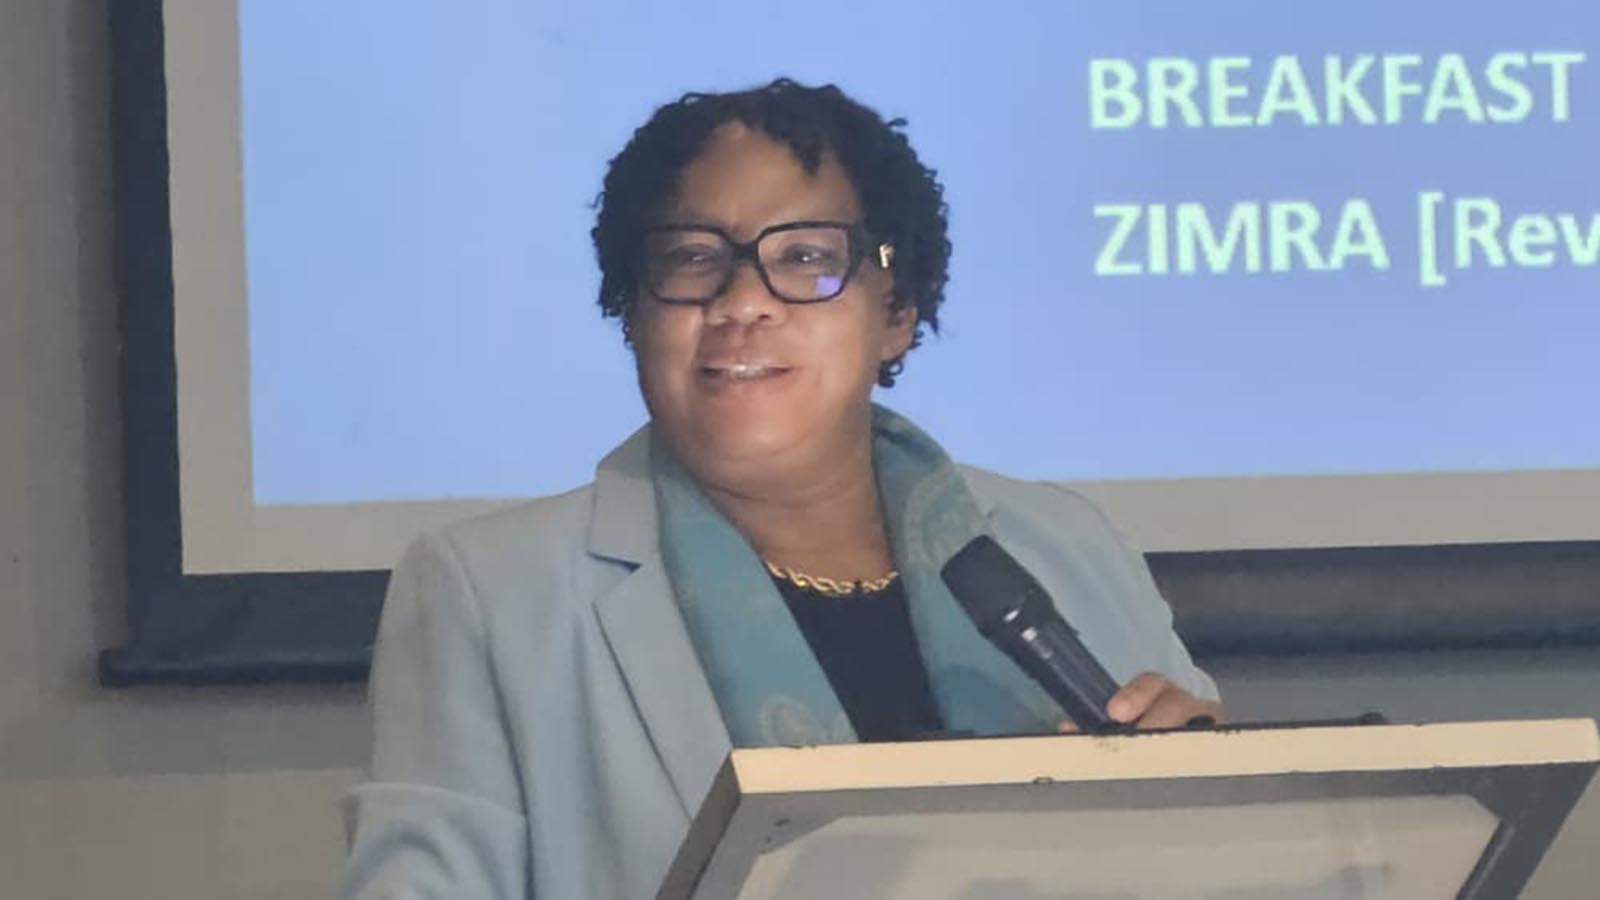
Zimbabwe has enacted the Domestic Minimum Top Up Tax, with effect from 1 January 2026, and regulations to operationalise it are expected before the end of next month, Commissioner Revenue Assurance Mrs Constance Shumbayawonda has said.
Addressing stakeholders at a breakfast engagement in Harare today, Mrs Shumbayawonda said the principal law was now in place and that reporting and processing under the Domestic Minimum Top Up Tax (DMTT) had been made seamless, with only the regulations outstanding.
“What is only left now is the regulations. We are in an advanced stage. Our chief director (from the Ministry of Finance Economic Development and Investment Promotion) is here. As soon as he is done with the regulations… we are hoping to push them through before the end of the coming month,” she said.
She said the introduction of the DMTT represented both a strategic measure to safeguard Zimbabwe’s taxing rights and an economic imperative to protect the domestic tax base in an increasingly interconnected global economy.
Mrs Shumbayawonda explained that before the legislation, if a multinational company operating in Zimbabwe paid an effective tax rate of less than 15 percent — for example, because of tax incentives or concessions offered by Zimbabwe — another country, such as the jurisdiction where its parent company is based, would potentially collect the additional tax needed to bring the effective rate to 15 percent.
“By electing the DMTT, we ensure that the primary rights to tax the profits generated right here in Zimbabwe remain with Zimbabwe,” she said. “This legislation prevents the flight of tax revenues, preserves fiscal sovereignty and ensures a level playing field.”
She said governments across the world had been responding to the challenges posed by base erosion and profit shifting by multinational enterprises that exploit cross-border mismatches to shift profits out of source jurisdictions into low-tax jurisdictions. In response, she said, the OECD/G20 Inclusive Framework developed the Two-Pillar Solution, with Pillar Two establishing a global minimum corporate tax rate of 15 percent.